

telebirr
by Ethio telecom SC
4.2
- Safety
- 100% Safe
- Category
- Business
- Ratings
- 4.2
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
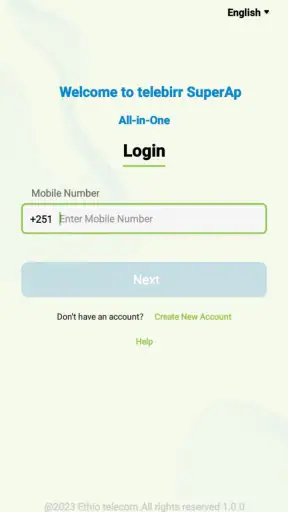
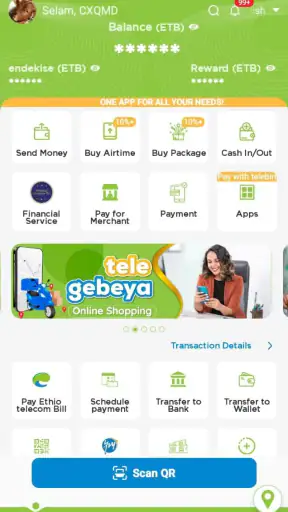
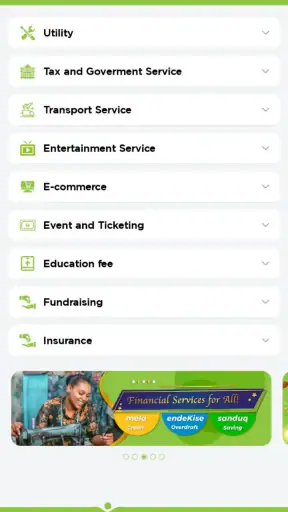
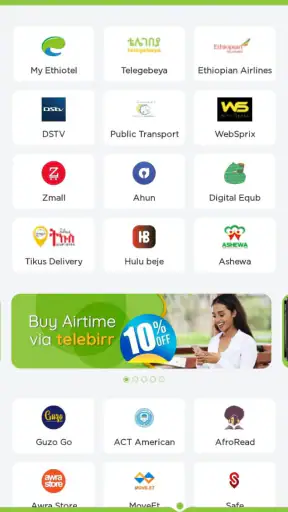
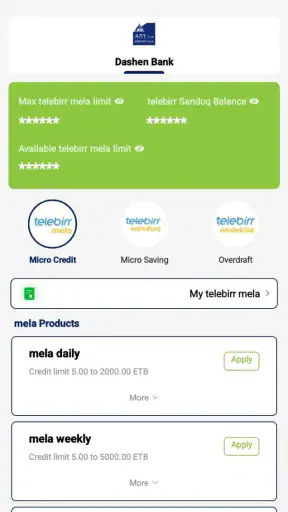
 Analysis by Getfullapps
My first impression of telebirr was that it is trying to become a regular part of everyday money management rather than a one-time utility. Developed by Ethio telecom SC, this free Business app is built around the telebirr SuperApp service and is available to everyone old enough to use a standard mobile device. I found the appeal easy to understand: instead of treating mobile money as something reserved for occasional transfers, the app encourages you to keep routine payments and money-related tasks in one familiar place.
That convenience matters most when a financial app becomes a habit. A service can look impressive during its first few days and still become irrelevant once the novelty disappears. My main question was therefore not whether telebirr feels useful at first, but whether it earns a permanent place on a phone. After spending time with it, I would describe it as a practical choice for people already connected to Ethio telecom’s mobile ecosystem, especially those who want a straightforward digital wallet experience rather than a collection of unrelated financial tools.
From an appealing first week to a lasting routine
I see this section as a shift from the curiosity of trying telebirr to the small decisions that make a financial app worth returning to. The useful test is not how many areas I explore, but whether one repeated task becomes easier without making me less careful. That distinction leads naturally to what can still matter once the first-week appeal has passed.
Why the first week feels useful
The first-week appeal comes from the idea of reducing small points of friction. When I need to handle a mobile-money task, I do not want to search through several services, remember which one supports a particular action, or switch between communication and payment tools unnecessarily. telebirr presents itself as a central doorway to that kind of activity, which makes the service easy to understand even before it becomes part of a daily routine.
Its position in the Business category is worth noting because the app is not framed as entertainment or social software. I approached it as a practical tool, and that changes the standard I use to judge it. A successful session is not one that keeps me browsing; it is one that lets me complete a money-related task with as little confusion as possible and return to the rest of my day.
The app is free, which removes an obvious barrier for someone deciding whether to try it. It is also marked for Everyone, so the presentation aims at a broad audience rather than a narrow professional group. In my experience, that broad positioning works best when the user wants familiar language and a direct path to an action, not a dashboard overloaded with financial terminology.
A realistic everyday scenario
Imagine a normal morning in which I need to send money to a family member, take care of a payment, and then check that the transaction has gone through before leaving home. The real value of a mobile-money app in that situation is not a flashy interface. It is the ability to open one service, complete the necessary steps carefully, and keep enough confidence in the result to move on.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
telebirr makes sense in that scenario because it is tied to a recognizable telecommunications provider and is designed as a broader SuperApp service. I would still slow down for every confirmation screen, especially when entering a recipient or amount. Speed is helpful, but financial actions should never be treated like casual taps. My practical advice is to review the destination and value before confirming, then keep the confirmation information available until the other person or service has acknowledged receipt.
This is one of the less obvious differences between a financial app and an ordinary convenience app: the best workflow includes a pause. telebirr may make the process feel quicker, but I would not let that encourage careless behavior. The app is most useful when it reduces unnecessary navigation while still leaving room for deliberate checking.
What the public response suggests
The app has reached over 10 million installs and holds a 4.2 average from around 98 thousand ratings. Those figures suggest that telebirr has moved beyond being a niche experiment and is being considered by a large mobile audience. I do not read popularity as proof that every person will enjoy the experience, but it does make the app easier to take seriously when comparing it with less established alternatives.
The number of ratings is also more informative than a handful of enthusiastic comments because a financial service has to work across many habits, phones, and levels of technical confidence. Still, an average score cannot tell me whether the app fits my exact needs. Someone who already uses another wallet successfully may gain little by changing, while someone who wants a single service connected to Ethio telecom may find the switch worthwhile.
Who should try it first
I would start with telebirr if I regularly use Ethio telecom services, want a mobile-money option associated with that provider, or prefer a single app over managing several separate tools. It may also suit family members who need a clear, repeatable way to handle everyday transactions without learning a complicated financial platform.
It is less compelling for someone who only needs occasional banking and already has a trusted alternative that covers those tasks. Switching has a cost even when an app is free: I have to learn a new layout, establish a new routine, and decide which service should become the main record of my activity. If an existing wallet already handles my payments reliably, telebirr needs to offer a meaningful improvement in convenience before I should move everything.
What remains valuable after the novelty fades
For me, lasting value comes from fit: whether the people I pay, the services I use, and the routines I already have make telebirr a sensible place to return. A helpful way to judge that is to notice which actions I actually repeat, rather than assuming a broader SuperApp role is automatically better. From there, the next question is what it takes to keep the app useful over time.
Month-to-month usefulness depends on repetition
After the first week, the question changes. I stop judging the app by how quickly I can discover its main idea and start judging it by how naturally it fits repeated tasks. A mobile-money service earns lasting space when I can return to it after several days away and still understand where to go, what needs checking, and how to confirm that an action succeeded.
That kind of familiarity is more important than visual novelty. I would rather have a stable routine for sending money or handling payments than an interface that constantly tries to impress me. telebirr’s strongest long-term case is therefore practical: if the people and services I deal with are already part of its ecosystem, each repeated transaction can reinforce the decision to keep it installed.
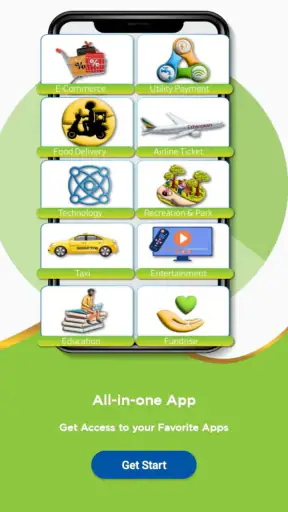
The SuperApp approach can be useful here because it suggests a wider role than a single-purpose wallet. However, breadth is only valuable when it saves time. If I have to search through too many sections for the action I use most, the larger design becomes a burden. My preferred setup would be to identify the few tasks I repeat and make those the center of my personal routine, rather than exploring every available area simply because it exists.
A useful habit for safer recurring use
One habit I would recommend is separating exploration from important transactions. When I have spare time, I can look through the app and learn where common functions live. When I am in a hurry, I should use only the paths I already recognize. This reduces the chance of selecting an unfamiliar option under pressure and makes the app feel more dependable over time.
I would also check transaction details immediately instead of relying on memory. For recurring payments or transfers, keeping a simple personal note of what I intended to do can help me notice a mistake early. This is not a special feature claim about telebirr; it is a sensible workflow for using any digital wallet, and it becomes especially valuable when an app gathers several money-related activities in one place.
Another practical trade-off is centralization. Having one main app can simplify my routine, but it also means I should not assume that convenience removes the need for backup awareness. I want to know how I will reach the recipient or service if a transaction needs clarification, and I prefer to keep important confirmation details until everything is settled. The app can streamline the action, but it cannot replace careful personal records.
How it compares with familiar alternatives
Compared with traditional cash handling, telebirr offers the obvious benefit of a digital process that can be used without physically passing money from one person to another. That can make remote support and planned payments easier. Cash, however, remains more immediate for people who prefer tangible control or who do not want to depend on an app-based routine.
Compared with a bank’s mobile application, telebirr may feel more focused on mobile-money behavior and telecommunications-linked use. A bank app can be the better choice when I need detailed account management, formal banking records, or services centered on a bank relationship. I would not replace a full banking tool with telebirr if my main needs belong to that category.
Compared with another digital wallet, the deciding factor is less about the word “wallet” and more about the network around it. If my family, customers, or regular payment destinations already use telebirr, the service becomes more convenient through shared familiarity. If they do not, another option may create fewer steps even if telebirr itself is well designed. The best choice is the one that matches the people and payments I actually deal with.
Why the current version matters to everyday users
The current version is 1.3.3.079, and the app supports Android 7.0 or newer. That makes it accessible to many users who are not carrying the latest phone. For me, broad device compatibility is important in a money app because replacing a phone should not automatically mean losing access to a familiar financial routine.
At the same time, anyone using an older device should keep realistic expectations. A newer service may feel less comfortable on hardware with limited performance, and a large SuperApp can demand more attention than a narrowly focused tool. I would test the everyday actions I actually need rather than judging the app by how many sections I can open. If those core actions remain clear and responsive on my phone, the supported operating-system range becomes a real advantage.
Maintenance, fatigue, and the cost of keeping it installed
I think the real cost of keeping a money app is less about its free price than the attention it asks for: remembering a routine, checking confirmations, and adapting when the experience changes. That effort is reasonable when the app removes friction from transactions I make regularly, but it can become needless clutter when I rarely use it. The balance between useful maintenance and app fatigue is what this section examines.
The maintenance burden is mostly behavioral
Keeping telebirr installed is easy; keeping it useful requires a little discipline. I need to remember my access details, protect the phone itself, and pay attention to confirmations instead of treating the app as an invisible background service. That maintenance is not unique to telebirr, but it is part of the real ownership experience and should be included in any decision to rely on it.
I would avoid installing it only because it is popular or because the SuperApp label sounds broad. A financial app earns its space when I use it repeatedly. If I open it once, become unsure where to go, and return to another wallet for every real transaction, it is adding clutter rather than value. The best test is simple: after the initial exploration, does it shorten a task I perform often?
Updates can also affect long-term comfort. The listed release date is May 1, 2021, while the app has continued to a newer current version. That combination tells me the product has an ongoing life rather than being a frozen release, but it also means I should expect the interface or workflow to evolve. I welcome improvements, yet I prefer to relearn a financial path carefully after a significant change instead of assuming that familiar buttons still lead to the same place.
Where fatigue can appear
The main source of fatigue is the tension between breadth and focus. A SuperApp can reduce the need for multiple installations, but every additional area can make the first screen feel busier. If I only want one common action, extra choices may slow me down. This is not a reason to reject telebirr, but it is a reason to create a personal routine and resist unnecessary wandering through the interface.
Another possible frustration is the emotional weight of financial mistakes. A small delay or unclear confirmation feels more serious when money is involved than when I am using a shopping or entertainment app. I would rather see a calm, predictable process than a highly animated one. When a step feels ambiguous, I stop and verify instead of tapping through quickly.
People who frequently move between different financial services may also experience fatigue from maintaining several balances, histories, or transaction habits. telebirr can simplify that situation if it becomes the main service, but it can make things feel more fragmented if it is added without replacing anything. Before installing it, I would decide which task it is meant to improve. A clear purpose prevents the app from becoming another unused icon.
When another option is better
I would choose a bank-centered application over telebirr when my priority is formal banking management rather than mobile-money convenience. I would choose a different wallet when the people I pay or receive from already use that service and the network effect saves me more effort. I would also stay with cash for very occasional, simple exchanges if adding a digital routine would create more work than it removes.
These are not criticisms of telebirr so much as boundaries around its best use. The app is strongest when its connection to Ethio telecom and its broader service design fit my real life. It is not automatically the best financial tool for every household, and its free price does not by itself justify keeping it installed.
My long-term verdict
After the first-week appeal fades, I think telebirr can earn lasting space when it becomes the familiar route for repeated mobile-money tasks. Its strongest qualities are its broad reach, free access, connection to Ethio telecom SC, and the practical promise of bringing more than one kind of activity into a single SuperApp experience. The large install base and solid average rating reinforce the impression that it has become a serious everyday option.
My recommendation is conditional but positive: try it if your contacts and regular payments fit the telebirr ecosystem, then judge it by the time and uncertainty it removes from your monthly routine. Do not keep it merely because it is installed, and do not let a wider feature set distract from the actions you actually need. I would give it a permanent place on my phone when it makes recurring transactions easier to organize than my current alternatives.
For someone seeking a practical mobile-money companion rather than a full replacement for every banking service, telebirr is worth considering. Its long-term value comes less from novelty than from repetition: one clear workflow, used carefully, by people who already have a reason to meet inside the same network. That is the point at which telebirr stops being another app to test and becomes a tool I would genuinely recommend to a friend.
Pros
- Fast mobile payments for bills, airtime, and everyday purchases.
- Supports transfers without requiring a traditional bank account.
- Growing merchant network makes cashless payments more convenient.
- Useful USSD access can help users without smartphones or data.
- Transaction history makes it easier to monitor spending and transfers.
Cons
- Availability and features may vary depending on location and account type.
- Some merchants may still prefer cash or lack reliable telebirr support.
- Transfer and withdrawal fees can add up with frequent use.
- Account verification may require personal details and valid identification.
- Service interruptions or network issues can delay payments and transfers.
FAQs for telebirr
What is telebirr and what can I use it for?
telebirr is a mobile money and digital payment service in Ethiopia that allows users to manage money through a mobile phone. Depending on account eligibility and available services, you can send and receive funds, pay bills, purchase airtime or data, make merchant payments, and access other financial services. Availability may vary by location, account type, and supported operators.
How do I register for a telebirr account?
Registration generally requires an eligible Ethiopian mobile number and identity verification according to the provider’s requirements. After installing or accessing telebirr, follow the sign-up instructions, enter your personal information, and create a secure PIN. You may also be able to register through authorized service points. Make sure your details match your identification documents to avoid verification or transaction problems.
Is telebirr safe for sending and receiving money?
telebirr uses account authentication and a personal PIN to help protect transactions, but users must still take precautions. Never share your PIN, one-time passwords, or verification codes with anyone, including people claiming to be support staff. Check recipient details before confirming a transfer, keep your phone secure, and contact official customer support promptly if you notice suspicious activity.
Are there fees, limits, or requirements for telebirr transactions?
Some telebirr services may include transaction fees, while others can have different pricing depending on the amount, transaction type, channel, or promotional terms. Daily and monthly limits may also apply, and these can depend on account verification and applicable regulations. Review the fee and limit information shown before confirming a transaction, since charges and policies may change.
What should I do if a telebirr transaction fails or my account is locked?
If a transaction fails, first confirm that you have sufficient balance, a stable connection, and the correct recipient or merchant details. Save the transaction reference and check whether the amount was reversed automatically. If the issue continues, use telebirr’s official support channels or visit an authorized service point. Do not repeatedly guess your PIN, as this may lock the account.

telebirr
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via telebirr@ethionet.et, visit https://www.ethiotelecom.et, or review their https://www.ethiotelecom.et/privacy-policy/.










